Total Loss in California: Signing Title Over to Insurance
If an insurance company pays a total loss settlement and takes your car, you generally sign the title over to the insurer. In California, that title goes to the DMV along with an application for a salvage certificate, which becomes the ownership document for the car. If you keep the car instead, the process changes: you apply for the salvage certificate yourself, and the insurer may deduct the car’s salvage value from the payment. The details below come from DMV guidance, the Vehicle Code and California insurance regulations. They are general information, not legal advice.
What does “total loss” mean in California?
DMV’s definition of a total loss salvage vehicle (Vehicle Code section 544) is a vehicle that has been wrecked, destroyed or damaged to the point that the owner or the insurance company considers it uneconomical to repair, and for that reason it is not repaired for the owner. When an insurer settles a claim on a vehicle like that, a salvage certificate is issued for it in place of the regular certificate of title.
The claim can be with your own insurer or with the other driver’s insurer. In either case, California’s insurance regulations (10 CCR section 2695.8) set standards for how total loss claims are evaluated.
Why does the insurance company get the title?
When an insurer pays a total loss, it generally takes over the car. DMV describes salvage pools as businesses that dispose of total loss vehicles received from, or on behalf of, insurance companies. Vehicle Code section 11515 says that when an insurance company makes a total loss settlement, the insurer, an authorized DMV occupational licensee or an authorized salvage pool must send DMV the properly endorsed title or other acceptable evidence of ownership, the license plates and a fee within 10 days of the settlement. DMV then issues a salvage certificate.
The timing rules run from the settlement. If an insurer cannot get the title, the statute gives it a separate route that starts after the owner accepts an offer, orally or in writing. Because of that, the title is usually signed over after you and the insurer agree on an amount, not before.
How does the title transfer work?
Most insurers send a packet with instructions for signing the vehicle over, so the steps below describe the general process rather than any one insurer’s paperwork.
- Find the title. If the car is paid off, the title is normally issued to the registered owner. If there is a loan, the lender typically holds the title record, often electronically (see the next section).
- Endorse the title. DMV requires a properly endorsed title or other acceptable evidence of ownership. Its procedures manual says the applicant’s signature is not required in the “new registered owner” space of the title, because the signature on the salvage application (REG 488C) is enough.
- Replace a lost title. DMV lists an Application for Replacement or Transfer of Title (REG 227) for a missing California title.
- Keep copies. It helps to keep copies of everything you sign and send.
The insurer or its designee then applies to DMV for the salvage certificate using the Application for Salvage Certificate or Nonrepairable Vehicle Certificate (REG 488C).
What if the car is financed or leased?
A lender with a lien on the car is the legal owner of record. DMV’s Electronic Lien and Title program keeps participating lienholders’ title records in electronic form, and when a lien is satisfied a lien satisfaction notice goes to DMV so the title can be issued. For paper titles, DMV has a Lien Satisfied/Legal Owner/Title Holder Release form (REG 166).
Because the lender’s interest is part of the title record, the insurer and the lender generally have to coordinate before the DMV paperwork is finished. DMV describes the insurance payoff as going to the insured and/or the lienholder, so how the settlement is split depends on your loan and the payoff amount. If the car is leased, ask the insurer who has to sign. Asking the insurer and the lender for the payoff figure in writing is a practical way to see where the money goes.
What if you keep the car?
Owners can choose to retain a total loss vehicle. When that happens, California law sets out several steps:
- The insurer must notify DMV that you kept the car, using the Salvage Vehicle Notice of Retention by Owner (REG 481), and tell you that you are responsible for applying for the salvage certificate.
- You must send DMV the properly endorsed title or other evidence of ownership, the license plates and a fee within 10 days of the settlement (Vehicle Code section 11515(b)), along with REG 488C.
- The settlement can reflect the salvage value. Under 10 CCR section 2695.8, the insurer may deduct the amount a salvage pool or dealer would pay for the car, and the settlement must include the fees to move the car to salvage status.
- The insurer must tell you in writing that the retention is reported to DMV, that it may affect resale and insured value, and that you may be able to seek a refund of unused license fees from DMV. If you ask, it must also give you the name of the salvage buyer.
If a salvage certificate is lost, DMV describes a duplicate application that uses REG 488C and a Statement of Facts (REG 256).
Does a release of liability apply?
DMV requires a Notice of Transfer and Release of Liability (REG 138) within five calendar days after you sell or transfer the title or interest in a vehicle and deliver possession to another owner (Vehicle Code section 5900). DMV says that once it is filed correctly, responsibility for parking and traffic violations and civil claims arising after the date of sale moves to the new owner. It can be filed online at dmv.ca.gov/nrl.
Whether to file one after a total loss pickup is a fair question for the insurer or DMV. The notice is not a transfer of title; the new owner still has to complete the transfer requirements.
What if the offer seems too low?
Before you agree, it helps to know how California regulates the valuation:
- A comparable vehicle is one of like kind and quality, made by the same manufacturer, of the same or newer model year, the same model type and a similar body type, with similar options and mileage.
- The settlement is based on the cost of a comparable vehicle less your deductible, and it must include applicable taxes and one-time transfer fees, plus license and other annual fees based on the remaining registration term.
- The insurer must itemize and explain in writing how it determined the comparable vehicle cost, and any adjustments must be itemized and documented.
- On a claim under your own policy, if you notify the insurer within 35 calendar days of receiving the payment or final offer that you cannot buy a comparable car for that amount, the insurer must reopen the file and follow set steps, unless it already identified a specific comparable car available at that price.
Because the title is usually signed after you and the insurer reach an amount, these questions can come up before the sign-over. A licensed attorney can explain how these rules apply to a particular claim.
If the crash also caused injuries, the car is only one part of the claim. Our guide to car accident claims in California covers filing deadlines, shared fault and insurance basics.
Sources
- California DMV, Vehicle Industry Registration Procedures Manual, 19.015 Definitions
- California DMV, 19.045 Notice of Retention by Owner, Salvage Vehicle
- California DMV, 19.075 Salvage Certificate
- California DMV, Total Loss Salvage and Non-Repairable Vehicles
- California DMV, Notice of Transfer and Release of Liability
- California DMV, Electronic Lien and Title Program
- California Vehicle Code section 11515, Justia
- California Code of Regulations, title 10, section 2695.8, Cornell LII
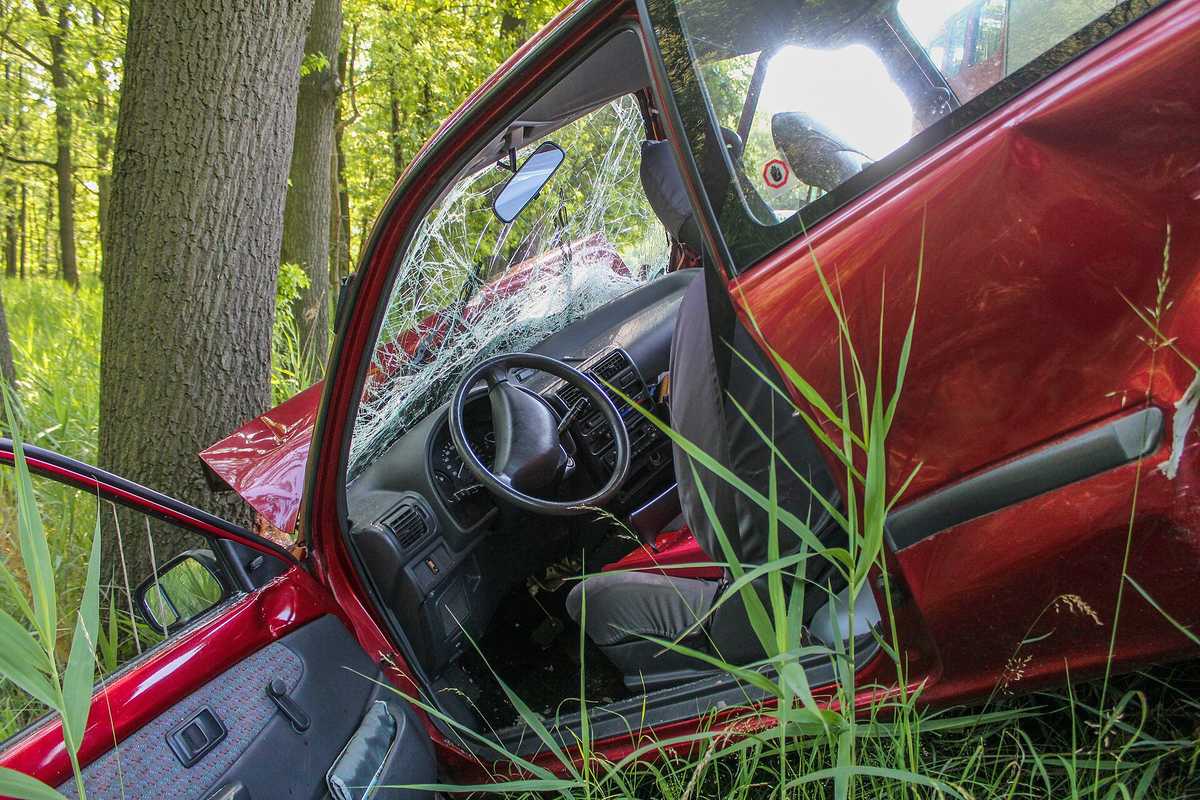
Photo: “Car collision with tree” by Rico Loeb, Wikimedia Commons, CC0 (resized and compressed).

Frequently asked
Do I have to sign my title over to the insurance company after a total loss?
Usually, yes, if the insurer pays a total loss settlement and takes the car. California law has the insurer, or a salvage pool it authorizes, send DMV the properly endorsed title or other evidence of ownership, the license plates and a fee within 10 days of the settlement. If you keep the car instead, a different DMV process applies.
Can I keep my car if it is declared a total loss?
Yes, California law addresses owners who keep a total loss vehicle. The insurer must tell DMV that you kept the vehicle and tell you that you are responsible for applying for a salvage certificate within 10 days of the settlement. California insurance rules also let the insurer deduct the car's salvage value from the settlement, and the insurer must disclose in writing that the retention is reported to DMV and may affect resale and insured value.
What if I still owe money on the car or it is leased?
A lender with a lien on the car is listed as the legal owner of record, and DMV releases the title when the lien is satisfied. DMV materials describe the insurance payoff as going to the insured and/or the lienholder, so ask the insurer and the lender for the payoff figure in writing. This article describes the process in general terms and is not advice about your loan or lease.
What is a salvage certificate?
DMV issues a salvage certificate instead of a title for a total loss salvage vehicle, and it becomes the ownership document. California defines a total loss salvage vehicle as one damaged so badly that the owner or insurer considers it uneconomical to repair, and it is not repaired for the owner. DMV issues the certificate in the name of the registered owner or the insurance company.
What can I do if the total loss offer seems low?
California insurance regulations require the insurer to explain in writing how it valued a comparable vehicle and to itemize adjustments. For a claim under your own policy, if you tell the insurer within 35 calendar days of receiving the payment or final offer that you cannot buy a comparable car for that amount, the regulation requires the insurer to reopen the file and follow set steps, with limited exceptions. Because the title is usually signed after you agree on an amount, you can ask questions or speak with a licensed attorney before agreeing.
Attorney Advertising. This article is general information, not legal advice, and does not create an attorney-client relationship. Prior results do not guarantee a similar outcome.